

How Geoeconomic Compression and Gateway Crackdowns Are Paralyzing Russia's Shadow Settlement Arteries
Section 1. The Assembly Point: From Raw Material Tankers to Digital Clearing
Previous installments of the Dialogue Party investigation exposed the physical mechanics used to breach the sanctions cordon: laundering metallurgical exports through ICBC networks and London LME warehouses, ship-to-ship (STS) crude transshipment in the Black Sea, and falsifying Rules of Origin certificates across transit hubs. Yet no shadow tanker fleet and no re-stamped HS tariff code operate in isolation. The core vulnerability of the Russian military-industrial apparatus in late 2026 lies neither along maritime lanes nor at loading berths, but in cross-border settlements.
The disconnection of key Russian financial institutions from SWIFT, sweeping designations onto the U.S. Treasury's OFAC SDN List, and relentless secondary sanctions pressure have effectively demolished traditional documentary letters of credit. Russian procurement entities can no longer rely on straight-through interbank wire transfers to pay for Chinese CNC machining tools, specialized microelectronics, or micro-turbojet engines destined for strike drones. Direct ruble or yuan transfers routed from Russian banks to Chinese state-owned lenders face compliance freezes stretching across months.
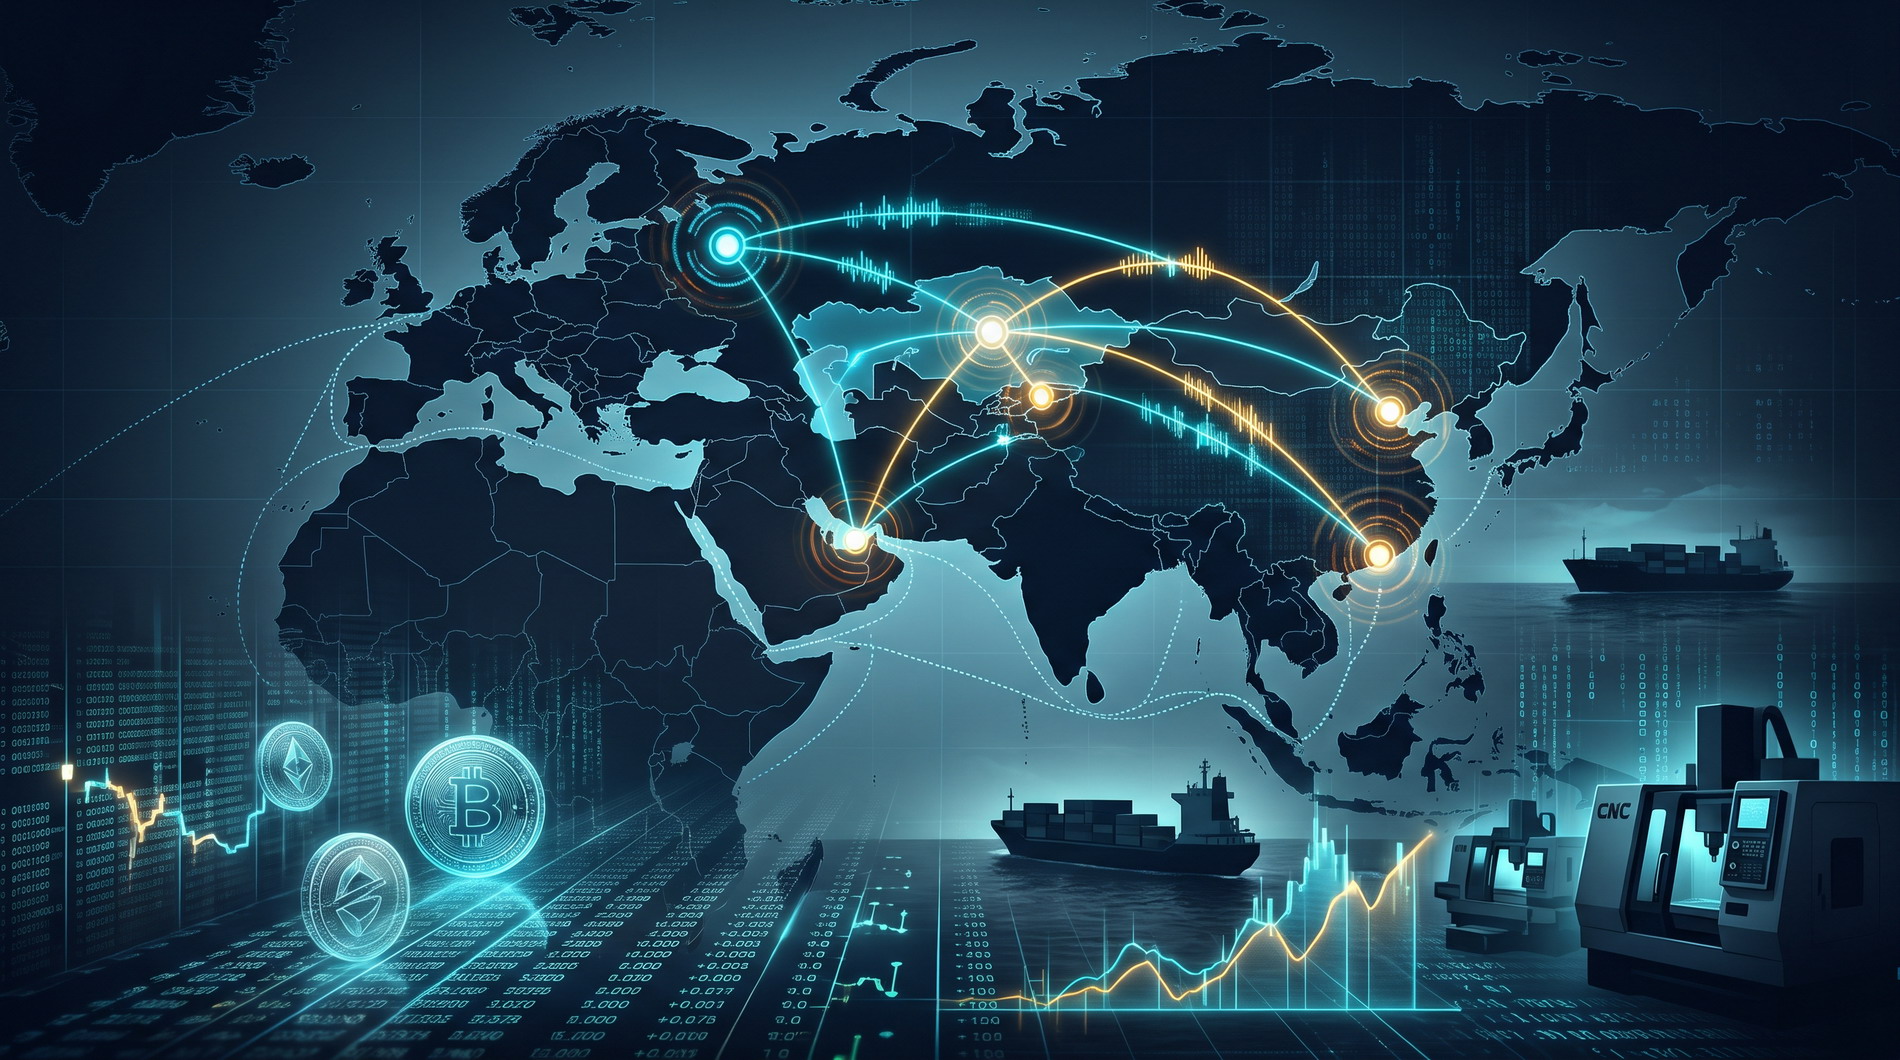
The Kremlin's countermeasure has been the deployment of a decentralized settlement surrogate — a shadow clearing ecosystem designated as the A7 Network. It has transformed international transactions from formal banking pipelines into a multi-tiered netting apparatus where non-custodial stablecoins serve as the digital clearing unit, minimizing the need for physical currency to cross international frontiers.
Section 2. Anatomy of the A7 Network: Fiat Drop Networks and Central Asian Corridors
The entry topology of the A7 Network is rooted deep within Russia’s domestic banking periphery, breaking down large capital flows into fragmented micro-transactions to evade both international surveillance and domestic regulatory scrutiny by the Central Bank of Russia.
1. The Domestic Ruble Accumulation Loop
- Retail P2P Processing and "Drop" Networks: Corporate fiat funds from industrial enterprises, electronics distributors, and intermediary fronts are split into hundreds of micro-transfers. Rerouted through automated retail gateways and debit cards held by private "drops," rubles flow swiftly into transit pooling accounts.
- Tier-2 Regional Banks: Capital aggregation takes place inside second-tier Russian commercial banks that maintain no international footprint and currently remain unlisted on Western blocking sanctions lists. Capital is masked behind synthetic contract descriptions: "freight forwarding services," "Asian market research consultancy," or interest-free intra-group promissory loans between interlocking shell companies.
2. The Central Asian Transit Bridge
Aggregated ruble balances are funneled outside the Russian Federation via correspondent banking links across Kazakhstan, Kyrgyzstan, and Uzbekistan:
- Nostro Account Corridors: Direct correspondent accounts link Tier-2 Russian lenders with regional Central Asian banks, executing instant swaps from rubles into Kazakhstani Tenge (KZT), Kyrgyzstani Som (KGS), or Uzbekistani Sum (UZS).
- AIFC Regulatory Gaps vs. Unregulated OTC Desks:
- In Kazakhstan, operations are partly channeled through corporate entities licensed within the Astana International Financial Centre (AIFC), legitimizing transactions under the guise of equity venture funding or digital asset acquisitions.
- In Bishkek and Tashkent, a parallel cash and wire Over-the-Counter (OTC) market operates with minimal friction. Local currency dealers purchase incoming fiat pools and convert them into stablecoins without comprehensive KYC/AML provenance reviews.
At this junction, the capital pool severs its formal legal ties with Russian import entities and re-emerges as high-velocity, borderless digital liquidity.
Section 3. The Stablecoin Layer: Dual-Layer Netting Architecture
The operational backbone of the A7 Network is rooted in dollar-pegged stablecoins (predominantly USDT minted on TRC-20 and ERC-20 protocols). Stablecoins serve as a friction-free settlement conduit, synchronizing outbound commodity shipments with illicit high-tech inbound procurement inside a self-balancing loop.
Off-Chain Netting Mechanics
- Crypto-Liquidity Fed by Commodity Flows: Unsanctioned exports of Russian refined copper cathodes (laundered via LME-connected channels) and petroleum products (discharged via offshore Black Sea STS operations) are purchased by overseas commodity trading desks. By contractual design, substantial tranches of these proceeds bypass correspondent fiat wires, liquidating directly into USDT deposited on non-custodial wallets within neutral jurisdictions.
- Elimination of Capital Repatriation: Rather than remitting currency balances back into Russia — a move that triggers primary sanctions enforcement and domestic currency surrender requirements — digital dollars remain anchored inside offshore liquidity pools controlled by A7 Network operators.
- Closing Inbound Import Invoices: When a Russian defense integrator or industrial client orders Chinese industrial multi-axis milling machines or miniature turbojet propulsion units (such as the Telefly TF-TJ2000A documented in Geran series long-range drones), they deposit rubles into the domestic entry gateway. Concurrently, A7 Network administrators deduct equivalent USDT allocations from offshore pools, releasing them to Asian procurement brokers.
- Structural Outcome: Physical fiat never traverses the border between the Russian Federation and the People's Republic of China. Trade imbalances are cleared entirely through off-chain and on-chain bilateral offsetting.
Section 4. Offshore Finalization: Hong Kong Desks, UAE Hubs, and PRC Industrial Hubs
The terminal phase demands translating decentralized digital tokens into clean, legally compliant operating capital acceptable to Chinese commercial and state-owned manufacturers.
- Dubai Financial Bridge (DMCC): The UAE acts as a primary liquidity rebalancing zone between Gulf energy buyers and Asian suppliers, providing an intermediary venue to sanitize contractual paperwork.
- The Hong Kong Gateway and CNH Swaps: Within Hong Kong's crypto-fiat OTC ecosystem, USDT balances are converted into offshore yuan (CNH) through corporate front structures. Armed with debt-assignment declarations or third-party agency agreements, Hong Kong intermediaries book these inflows as standard international commercial proceeds.
- PRC Domestic Settlement (CIPS / CNAPS): Once inside the Hong Kong banking circuit, funds are dispatched to manufacturers in Shenzhen, Ningbo, and Shanghai across China’s domestic interbank settlement clearing channels. To corporate compliance controllers at Chinese factories, the payment arrives as an unremarkable, fully domestic B2B settlement from an Asian trade partner, bearing no references to Russian end-users, sanctioned logistics hubs, or military-industrial procurement.
Section 5. Interactive Topology Dashboard
The interactive investigative module below (developed by Andriy Bespalov, hosted on Railway) details the physical geography of settlement gateways, tracks the dual-layer commodity-technology balancing loop, and visualizes the systemic collapse of clearing margins:
(Use the header controls inside the module to toggle between the Leaflet Geographic Gateway Map, the Sankey Liquidity Flowchart, and the Physical Commodity Layer. Adjust the Cost & Latency Slider to trace the escalation of intermediary friction between 2024 and late 2026).
Section 6. The Sanctions Tax: Geoeconomic Compression and Structural Collapse
Despite the structural sophistication of the A7 Network, by late 2026 the architecture has entered an acute phase of geoeconomic compression. The shadow financial arteries engineered to circumvent Western oversight are fracturing under the weight of their own escalating friction.
1. The Friction Explosion
- During 2023–2024, when enforcement across Central Asia and the Gulf was nascent and fragmented, the all-in transaction cost for running funds end-to-end (from rubles deposited in Moscow to cleared yuan in Shanghai) stood at 5% to 2.5%, maintaining viable margins for grey-market hardware procurement.
- By late 2026, aggregate intermediary toll rates surged to 0% – 12.5%+. Every intermediary node now bills prohibitive risk premiums against OFAC secondary sanctions; Russian domestic drop networks face elevated operational costs due to anti-fraud account freezes, while Hong Kong OTC brokers levy aggressive surcharges to process high-risk wallet clusters.
2. Liquidity Chokepoints and Smart-Contract Interdiction
- Blockchain intelligence firms (Chainalysis, Elliptic) deploy automated heuristic clustering to map non-custodial wallet clusters tied to strategic Russian commodity netting.
- Stablecoin issuer Tether increasingly executes contract-level blacklisting freezes against designated addresses following directives from Western law enforcement. The sudden freezing of a single $15M–$20M liquidity pool instantaneously paralyzes dozens of outstanding procurement contracts across the supply pipeline.
3. Latency Penalties and Supply Disruption
- Average transaction cycle latency expanded from 24–72 hours in 2024 to 14–28 days by late 2026.
- Protracted payment processing drains operational working capital from Russian procurement entities. Compounded by aggressive monetary tightening by the Central Bank of Russia (a 14% policy rate paired with structural domestic liquidity deficits), a month-long capital freeze renders long-distance supply chains economically unviable.
Conclusion of the Investigation Series
Russia’s shadow financial networks are suffering the same fate as its maritime logistics corridors. While the initial phases of the war allowed Moscow to bypass trade controls through ad-hoc brokers and shell companies, by late 2026 sanctions circumvention has evolved into an unsustainable overhead burden. With transaction tolls crossing the 10% threshold, crypto-asset blacklists expanding, and regional correspondent banking windows shutting down, the economic viability of shadow trade has collapsed — confronting Russia's defense-industrial sector with inevitable, structural material shortages.




Залишити коментар